

Uphold: Buy BTC, ETH and 300+

- 8.35K Reviews
- 4.4
- Downloads
- 5,000,000+
Our take on Uphold: Buy BTC, ETH and 300+ from Appgk
I found Uphold most useful when I treated it as a practical bridge between ordinary money and digital assets, rather than as a complete replacement for a bank or a specialist trading platform. The app is built by Uphold and sits in the finance category, with a free download and an Everyone age rating. Its central appeal is simple: it gives me one mobile place to move from a familiar currency toward assets such as Bitcoin and Ethereum, then manage those holdings from the same account.
That simplicity is also where expectations need careful handling. Buying an asset can feel quick once everything is ready, but the first use is not always quick. Account checks, payment-method setup, identity details, network selection and transaction status can all interrupt the smooth path suggested by the short store summary. My strongest advice is to prepare before attempting an important transfer. Do not use a first-time purchase as an emergency payment plan.
Where the smooth experience usually breaks
The most common frustration is not necessarily a broken screen. It is a mismatch between what the user expects to happen and what the app needs before allowing the next step. Someone opening it for the first time may expect to choose Bitcoin, enter an amount and finish immediately. In practice, finance apps need enough account information and transaction context to process activity safely, so a new account may involve several checks before it is ready for regular use.
I would separate three different situations: an account that is still being prepared, a payment method that has not completed its own setup, and a transaction that has already been submitted but is still progressing. They can look similar when all I see is a button that remains unavailable or a balance that has not changed. Treating each one as a generic error often leads to repeated taps, duplicate attempts or unnecessary panic.
Best Parts of Uphold: Buy BTC, ETH and 300+
Things to Keep in Mind About Uphold: Buy BTC, ETH and 300+
Another point that deserves attention is the difference between an in-app balance and a completed movement outside the app. A purchase can appear to be in progress rather than instantly settled, while a transfer involving a digital-asset network may have its own processing time. I always check the transaction record before trying again. That small habit prevents the expensive mistake of submitting a second transaction simply because the first one was not immediately visible in the balance.
The app’s broad asset focus is convenient, but it can also make the screen feel more complicated than a single-purpose Bitcoin wallet. The right asset, currency and destination all matter. If I am moving an asset to an external wallet, I read the destination details slowly instead of relying on memory from a previous transfer. A familiar-looking name is not enough; the asset and its supported network need to match.
News and Features Related to Uphold: Buy BTC, ETH and 300+

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
News
Moovit Review: A More Reliable Way to Navigate Everyday Transit
News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
Why a quick purchase can still require patience
The phrase “from dollars to Bitcoin in seconds” captures the intended direction of the experience, but I would not read it as a promise that every account, payment method or transfer will complete in seconds. The app can make the order process feel direct while the surrounding checks and settlement steps continue in the background. This distinction matters most when the money is needed for a time-sensitive purchase or when a user is watching a rapidly changing market.
I also avoid judging the app solely by the speed of the first screen. The more useful question is whether I can understand what happened after pressing the button. Clear transaction history, a visible status and a record of the selected asset are more important to me than a flashy purchase animation. When something feels delayed, I look for the transaction’s current state before assuming the app has lost the order.
Don't want to read the full review?
What I check before creating a payment problem
Before adding money, I make sure the funding source is available for the type of transaction I am attempting and that its details are entered exactly as required. I use a stable connection, update the app when an update is offered by the platform, and avoid switching repeatedly between Wi-Fi and mobile data during a confirmation step. These are ordinary precautions, but they remove a surprising number of false alarms.
I also keep the first transaction deliberately small. That is not a claim about a required minimum or a recommended investment amount; it is simply a sensible way to learn the workflow without putting an important sum at risk. A small test helps me confirm that the account, funding route and intended asset are all behaving as expected before I make the process part of a regular routine.
Screenshots
Setup checks that save time later
The initial setup deserves more care than it usually receives. I enter personal information consistently, using the same details I would use for other legitimate financial services. If the app asks me to review or confirm something, I do that before attempting more purchases. Repeatedly abandoning the setup halfway through creates uncertainty about what has actually been completed.
It is also worth deciding what role the account will play. If I only want occasional exposure to a digital asset, I can keep the workflow simple and focus on buying, reviewing the balance and understanding how to sell. If I expect to move assets to another wallet, I plan that separately and learn the destination requirements before buying. This avoids the beginner mistake of purchasing first and only later discovering that the intended external destination needs a particular asset or network.
For security, I use a unique password, protect the phone itself and avoid signing in on a device that other people control. I do not share verification codes or approve an action merely because a message sounds urgent. Those precautions are especially important in a finance app because a convincing scam can look like a technical support request. The app cannot compensate for credentials handed to someone else.
Understanding the cost before confirming
I pay close attention to the final review screen rather than judging a transaction by the headline amount alone. The amount spent, the amount of the selected asset and any displayed charges should be read together. A purchase that looks inexpensive in isolation may be less attractive when the total cost, conversion rate and intended holding period are considered.
There are also in-app purchases listed for the app, ranging from $4.99 to $49.99 per item. I would not confuse those with the underlying value of an asset or assume that installing the app means I must buy anything inside it. The app is free to install, but using a finance service still requires attention to the transaction details shown at the moment of action.
Market movement adds another layer. The value I see after buying can change because the asset’s market price changes, not because the app has malfunctioned. I avoid making a second purchase simply to “fix” a balance that moved with the market. Instead, I compare the transaction record with the current market value and decide whether the original plan still makes sense.
A realistic first-week routine
My preferred routine is to install the app, complete the account preparation, inspect the available screens without rushing into a purchase, and then use a modest test transaction. After that, I wait until the activity is clearly recorded before deciding whether to continue. I save the transaction details for my own records and make a note of exactly which asset I selected.
On the next use, I review the balance and history before adding more money. This creates a simple personal audit trail: what I intended, what I paid, what I received and whether the action completed. It is more reliable than remembering the appearance of a confirmation screen. For anyone new to digital assets, this habit is one of the most useful features of the workflow even though it is something the user has to practice.
Recovering when a transaction seems stuck
When an action appears stuck, I first stop pressing the purchase or transfer button. I check whether the transaction is listed and whether its status has changed. Then I verify that the balance has not already been updated and that I have not received a confirmation elsewhere. This simple pause is important because repeating an action can create a second transaction rather than repairing the first.
If the screen itself behaves strangely, I close and reopen the app, confirm that the phone has a reliable connection, and try again later rather than changing several things at once. I also check whether the problem affects one transaction or the whole account. A single delayed action points to a different investigation than a login issue or a screen that fails across the app.
I keep the relevant details together before seeking help: the approximate time, the selected asset, the amount, the funding route and any transaction identifier shown in the app. I never send passwords or security codes in a support conversation. Describing the exact step where the process stopped is much more useful than saying only that “it does not work.”
Transfers need a separate mental checklist
Buying inside the app and sending an asset to an external destination are not the same workflow. For a transfer, I verify the receiving address character by character and confirm that the asset and network are compatible. I begin with a small test when the destination is new. A wrong destination is not something I expect a restart or a reinstall to repair.
I also avoid assuming that an external wallet will display a transfer immediately. The app may show that an action was submitted while the receiving service still needs to process or display it. I compare the transaction status and identifier with the receiving wallet’s records before taking further action. This is a practical distinction between an app problem and a destination or network delay.
One subtle advantage of keeping this checklist is that it makes the app easier to use repeatedly. I can save my own verified notes about a destination, but I still compare them with the current transfer screen every time. Copying an old detail without checking the present asset and network is convenient until it is not.
When the app is not the cause
Some apparent failures originate outside the application. A bank or card provider may decline a payment, a network connection may interrupt a confirmation, an external wallet may be slow to display an incoming transaction, or the asset’s market value may change while an order is being processed. In each case, reinstalling the app is unlikely to solve the underlying issue.
I use a process of elimination. If I can open the account and view earlier activity, the issue may be limited to the payment method or the specific transaction. If the funding source shows a decline, I investigate that route rather than repeatedly submitting the same request. If a transfer has a record and identifier, I investigate its destination and status before concluding that the app lost it.
Phone settings can matter too. A nearly full device, an outdated operating system, unstable connectivity or aggressive battery restrictions can interfere with any finance app’s normal behavior. Uphold supports devices running Android 8.0 or later, so I check the phone’s operating system before assuming every issue is account-related. I also keep enough free space for normal app operation and avoid using a public connection for sensitive financial actions.
There is a difference between a technical problem and a decision problem. If I bought an asset and its value fell, that is not evidence that the app calculated the balance incorrectly. If a transfer was sent to an address I did not verify, the correct response is not to keep tapping resend. Separating these cases protects both my money and my time.
Who benefits most from this approach
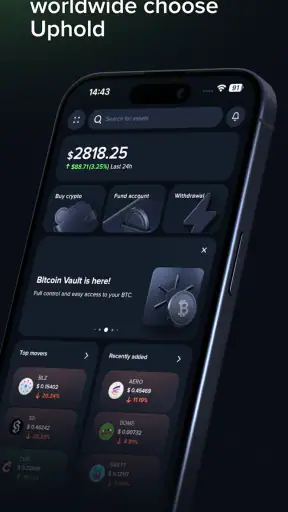
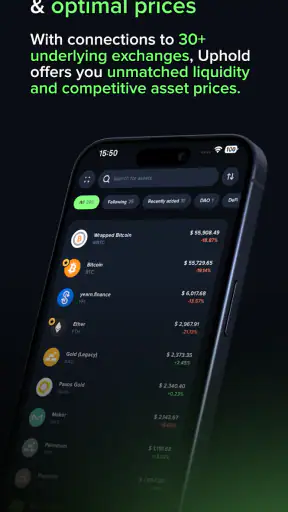
I see the app as a good fit for someone who wants a straightforward mobile entry point for moving between traditional currency and digital assets, and who values having several asset choices in one finance app. It can suit a person who prefers a guided purchase flow over managing a separate exchange interface, provided that person is willing to read confirmations and understand the difference between holding an asset and transferring it.
It is less suitable for someone looking for advanced charting, complex order types or a trading workstation. A specialist exchange may be better for active traders who need detailed market tools and more control over execution. A conventional bank may be a better choice for someone whose priority is stable cash management, familiar deposit protection arrangements and everyday bill payments rather than digital-asset access.
I would also hesitate to recommend it as a first choice for anyone who cannot tolerate price volatility or who expects every transaction to be reversible. The app makes access easier, but it does not remove the risks of the assets being bought. New users should decide how much loss they could genuinely accept before they fund an account, not after a market move makes that question uncomfortable.
My practical verdict after using it
Uphold: Buy BTC, ETH and 300+ is a useful finance app when its role is kept clear: it is a convenient access point for buying and managing digital assets, not a guarantee of instant settlement or a substitute for careful financial decisions. I like the directness of the mobile workflow, especially for someone who wants to begin with a modest purchase rather than learn a complicated trading terminal.
The app has also built a substantial user base, with an average rating of 4.4 from around 74 thousand ratings and more than 5 million installs. Those figures suggest that the basic experience works for many people, but they do not remove the need to check each transaction personally. Reviews and popularity can tell me that an app is widely used; they cannot tell me whether a particular funding source, destination wallet or market decision is right for my situation.
Its current version is 6.103.0, and the app has been available since December 29, 2015. I would keep it updated through the normal app store process, but I would not expect an update to solve an issue caused by a declined payment, an incorrect address or a changing market price. Troubleshooting works best when I identify the stage of the process first.
My final recommendation is conditional but positive. Install it if you want a free, mobile-first way to explore digital assets and you are prepared to slow down at the important moments. Start with setup, confirm the funding method, make a small test, inspect the record and treat external transfers as a separate operation. Skip it in favor of a bank or a more advanced exchange if your needs are conventional cash banking or professional-style trading. Used with those boundaries, it is approachable; used as a shortcut around financial risk, it is the wrong tool.
Uphold: Buy BTC, ETH and 300+ FAQ
What is Uphold: Buy BTC, ETH and 300+?
Uphold is a multi-asset financial app that lets users buy, sell, hold, and exchange cryptocurrencies such as Bitcoin and Ethereum, along with other supported digital assets. Depending on your region, it may also provide access to precious metals, national currencies, and additional financial services. The available features, assets, and account requirements can vary by country.
Is Uphold safe and legitimate to use?
Uphold is an established digital asset platform that uses account security measures such as identity verification, encryption, two-factor authentication, and transaction monitoring. However, no financial app is completely risk-free. Cryptocurrency prices can change rapidly, and users should enable all available security options, protect their recovery details, verify payment information, and understand the platform’s fees and policies before depositing money.
How do I buy Bitcoin or Ethereum through Uphold?
After creating and verifying an account, users can generally connect an eligible payment method, choose Bitcoin, Ethereum, or another supported asset, enter the amount, review the quoted price and applicable fees, and confirm the transaction. Payment methods and limits depend on location and verification status. Always check the final transaction summary carefully before approving a purchase.
What fees does Uphold charge?
Uphold may apply spreads, trading fees, network charges, withdrawal fees, or payment-processing costs depending on the asset, transaction type, payment method, and country. The exact amount can change and is normally displayed before you confirm an order. Because the quoted price may include a spread, compare the total cost shown at checkout rather than relying only on the advertised asset price.
Can I withdraw my cryptocurrency from Uphold to an external wallet?
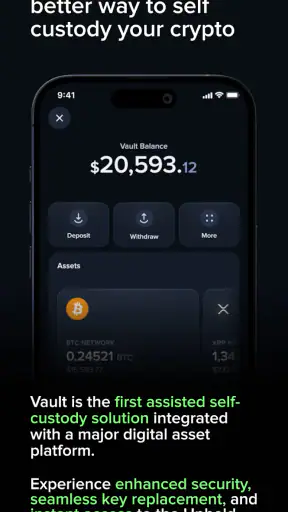
In supported regions and for eligible assets, Uphold may allow users to send cryptocurrency to an external blockchain wallet. Availability can depend on the asset, network, account status, and local regulations. Blockchain transfers are usually irreversible, so carefully confirm the wallet address and selected network before sending funds. Incorrect details may result in permanent loss, and network fees may apply.











